
Rate moves and refinance waves: how to prepare your LO website
Refinance marketing for loan officers: what a decade of Freddie Mac PMMS data shows, and how to prepare your site for the next refi wave.
 Ines CallowayDesign lead, Mortgage Website ShopPublished · Updated · 5 min read
KEY TAKEAWAYS
- Annual average 30-year rates (our averages of Freddie Mac PMMS weekly data) swung from 2.96% in 2021 to 6.81% in 2023, then stayed above 6%.
- In the most recent weeks the 30-year average rose again, to 7.40% on 2026-10-15, so refinance demand depends on where rates go next.
- Prepare before rates move: a refinance page, a break-even calculator, a rate-alert sign-up and instant follow-up.
- Never promise rates; show break-even maths and invite a personal review.
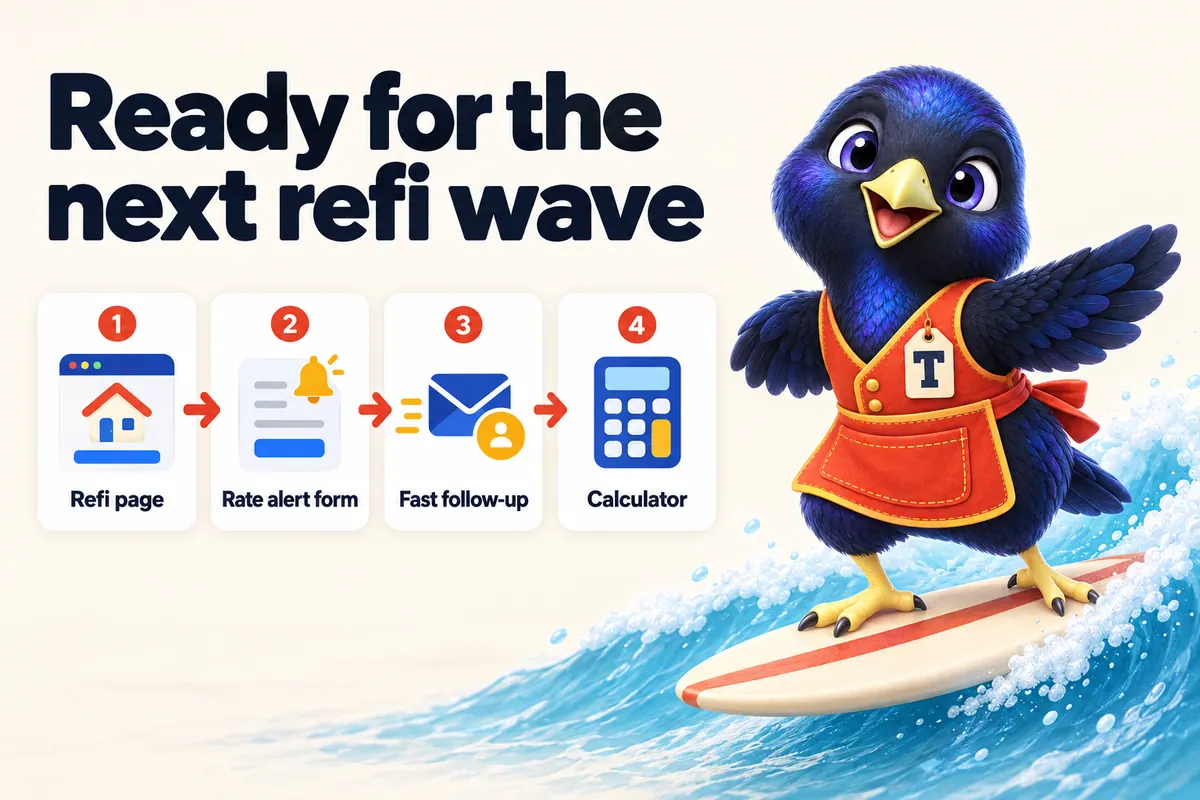
Refinance demand follows rates, and rates move faster than websites get rebuilt. The loan officers who capture a refinance wave are usually the ones whose site was ready before it started: a clear refinance page, a break-even calculator, a way to sign up for alerts, and instant follow-up.
We downloaded Freddie Mac’s historical weekly Primary Mortgage Market Survey (PMMS) data and averaged it by year and quarter to show how much rates have moved. The averages below are our calculations from Freddie Mac’s weekly figures.
30-year fixed average, latest week
Freddie Mac PMMS, 2026-10-15
30-year fixed average a year earlier
Freddie Mac PMMS, 2026-10-15
15-year fixed average, latest week
Freddie Mac PMMS, 2026-10-15
How much have mortgage rates moved?
A lot. Annual average 30-year rates fell to their lowest point of the decade in 2021, more than doubled by 2023, and have stayed above 6% since.
- 30-year fixed
- 15-year fixed
Source: Freddie Mac Primary Mortgage Market Survey, historical weekly data (downloaded 2026-10-19). Simple averages of weekly survey rates computed by Mortgage Website Shop. 2026 and 2026 Q4 are year/quarter to date through 2026-10-15.
Show the data table
| Point | 30-year fixed | 15-year fixed |
|---|---|---|
| 2016 | 3.65% | 2.93% |
| 2017 | 3.99% | 3.27% |
| 2018 | 4.54% | 4% |
| 2019 | 3.94% | 3.39% |
| 2020 | 3.11% | 2.6% |
| 2021 | 2.96% | 2.27% |
| 2022 | 5.34% | 4.58% |
| 2023 | 6.81% | 6.11% |
| 2024 | 6.72% | 5.96% |
| 2025 | 6.6% | 5.78% |
| 2026 | 6.48% | 5.82% |
| Year | 30-year fixed | 15-year fixed |
|---|---|---|
| 2016 | 3.65% | 2.93% |
| 2017 | 3.99% | 3.27% |
| 2018 | 4.54% | 4.00% |
| 2019 | 3.94% | 3.39% |
| 2020 | 3.11% | 2.60% |
| 2021 | 2.96% | 2.27% |
| 2022 | 5.34% | 4.58% |
| 2023 | 6.81% | 6.11% |
| 2024 | 6.72% | 5.96% |
| 2025 | 6.60% | 5.78% |
| 2026 | 6.48% | 5.82% |
Rate swings of that size change who can benefit from refinancing almost overnight. A homeowner who bought or refinanced at a high rate becomes a refinance candidate when rates fall far enough to cover closing costs within a reasonable time.
What do the most recent quarters show?
Quarterly averages smooth out the weekly noise and show the direction of travel.
Source: Freddie Mac Primary Mortgage Market Survey, historical weekly data (downloaded 2026-10-19). Simple averages of weekly survey rates computed by Mortgage Website Shop. 2026 and 2026 Q4 are year/quarter to date through 2026-10-15.
Show the data table
| Label | 30-year fixed |
|---|---|
| '24 Q1 | 6.75% |
| '24 Q2 | 7% |
| '24 Q3 | 6.51% |
| '24 Q4 | 6.63% |
| '25 Q1 | 6.83% |
| '25 Q2 | 6.79% |
| '25 Q3 | 6.57% |
| '25 Q4 | 6.23% |
| '26 Q1 | 6.11% |
| '26 Q2 | 6.41% |
| '26 Q3 | 6.68% |
| '26 Q4 | 7.36% |
Rates dipped in early 2026, then climbed through the third quarter and into October, reaching 7.4% in the week of 2026-10-15. Nobody can tell you where they go next, and you should never promise borrowers a rate. What you can do is be ready for either direction.
What should a refinance-ready website include?
Five pieces, all live before the market moves.
- A refinance page that explains, not sells. Rate-and-term versus cash-out, when it makes sense, what it costs, how long it takes.
- A break-even calculator. Current balance, current rate, new rate, closing costs: monthly savings and months to break even, labelled as an estimate.
- A rate-alert sign-up. Name, contact details, target payment and consent wording, feeding your CRM.
- Instant follow-up. An automated reply within moments, then a personal call.
- A cash-out page. Different goals, different questions, its own FAQs.
Two ways to meet a refi wave
Scramble when rates drop
Pros
- No upfront work
Cons
- Pages built in a rush
- Leads go to faster competitors
- No list of interested homeowners
Best for: Nobody, ideally
Ready in advance
Pros
- Alert list already built
- Calculator answers the first question
- Follow-up is instant
Cons
- Requires a little work now
Best for: Any LO with past clients or refinance volume
How should you talk about rates on your site?
Carefully. Advertising a specific rate or payment can trigger additional disclosures under Regulation Z and must be accurate and current. The safer, more useful approach is to cite a dated public benchmark (like the PMMS average, clearly labelled), explain break-even maths, and invite homeowners to request a personal review. That is honest, durable content that does not go stale when rates move.
A refinance prep checklist
| Item | Why it matters | Ready? |
|---|---|---|
| Refinance and cash-out pages | Answer the first questions in search and AI answers | ☐ |
| Break-even calculator | Shows whether a refinance pencils out | ☐ |
| Rate-alert sign-up with consent | Builds a list before the wave | ☐ |
| Instant follow-up sequence | Speed wins in a crowded market | ☐ |
| Past-client email plan | Your warmest audience | ☐ |
| Compliance review of rate language | Avoids trigger-term problems | ☐ |
Who becomes a refinance candidate when rates fall?
Refinance candidates are usually homeowners whose current rate is meaningfully higher than what the market offers, and who expect to keep their loan long enough for the savings to repay the closing costs. Because annual average rates were above 6% in 2023, 2024 and 2025 according to our averages of Freddie Mac PMMS data, many homeowners who bought or refinanced in those years hold rates that would become refinance candidates if the market fell far enough.
Other homeowners refinance for reasons that do not depend only on rates: removing mortgage insurance, switching from an adjustable to a fixed rate, shortening the term, or taking cash out for renovations or debt consolidation. A good refinance page addresses each of those motivations separately.
How does a break-even calculator help conversion?
A break-even calculator answers the first question every homeowner has: is it worth it? Instead of asking for contact details up front, it shows monthly savings and the number of months to recover closing costs, using the homeowner’s own numbers. When the answer looks promising, the natural next step is a personal review, and the homeowner arrives already understanding the trade-off.
Make sure the calculator is labelled as an estimate, explains its assumptions, and cites the source and date of any example rate.
How do you build a rate-alert list responsibly?
A rate-alert list is one of the most valuable assets a loan officer can build before a refinance wave, but it must be built with consent.
- Ask for clear permission. The sign-up should say exactly what you will send and how often.
- Collect only what you need. Name, email or phone, current balance range, target payment.
- Send useful updates, not blasts. A short note when the market moves meaningfully, with a link to the break-even calculator.
- Honour opt-outs instantly. Especially for texts.
- Keep it in your CRM. So every alert and reply is on the contact’s record.
What should the follow-up look like in a wave?
When a wave arrives, many lenders contact the same homeowners at once. Speed and clarity win. A good sequence: an instant reply acknowledging the request, a link to book a call, a short personal call or voicemail within the same business day, and a written summary of options after the call. AI chat and text assistants can handle the first reply at any hour, provided they never quote rates and always hand off to a licensed loan officer.
How should past clients be approached?
Past clients are your warmest audience. If they have agreed to hear from you, send a short, personal note when rates move meaningfully: what changed, a link to run their numbers, and an offer to review their loan. Avoid generic rate blasts. A message that references their situation (“you closed your purchase in 2024”) shows care and gets far better responses than a mass email.
How should content be updated when rates move?
When rates move quickly, the worst thing a site can do is display stale numbers. Avoid hard-coding rates into pages. If you reference a benchmark, label it with its source and date (for example, “the Freddie Mac PMMS 30-year average was 7.4% in the week of 2026-10-15”) and update it on a schedule, or link to the benchmark instead. Evergreen explanations of how refinancing works, what break-even means and when cash-out makes sense will stay accurate no matter where rates go, and they are exactly the content search engines and AI assistants prefer to quote.
A simple 30-day plan
If you want to be ready within a month, work through this order:
- Week 1: publish or refresh your refinance and cash-out pages, written answer-first with FAQs.
- Week 2: add a break-even calculator and a rate-alert sign-up with consent wording approved by compliance.
- Week 3: set up instant follow-up for refinance enquiries, including an automated first reply and a booking link.
- Week 4: prepare a short, personal email for past clients who have agreed to hear from you, and a landing page for any refinance ads.
After that, review the pages monthly and update benchmark references whenever you mention them.
The bottom line
You cannot control rates, but you can control whether your site is ready when they move. Build the refinance page, the calculator, the alert list and the follow-up now, cite rates only as dated benchmarks, and let the maths do the selling. See the Forge design, try the refinance break-even calculator, or set up lead funnels for refinance campaigns.
Frequently asked questions
What is a refinance wave?
A period when falling mortgage rates make refinancing worthwhile for many homeowners at once, leading to a surge of refinance applications.
How should loan officers prepare their websites for a refi wave?
Publish a clear refinance page, add a break-even calculator, offer a rate-alert sign-up with consent, and set up instant follow-up so every enquiry hears back quickly.
What does the Freddie Mac PMMS measure?
The Primary Mortgage Market Survey reports weekly average rates for 30-year and 15-year fixed mortgages based on applications submitted to Freddie Mac. It is a widely used benchmark, not a quote.
Can I advertise refinance rates on my site?
Advertising a specific rate or payment brings additional disclosure requirements and must be accurate and current. Many loan officers avoid publishing rates and focus on break-even explanations instead.
What is a refinance break-even point?
The number of months it takes for the monthly savings from a new loan to repay its closing costs. If you keep the loan longer than that, the refinance pays off.
What is a rate-alert sign-up?
A short form where homeowners leave their details and target payment, with consent, so you can contact them when the market moves toward their goal.
Should I email my past clients when rates drop?
Yes, if they have agreed to hear from you. A short, useful note with a break-even link is better than a generic rate blast.
How quickly should I respond to refinance enquiries?
As fast as possible. In a wave, many lenders compete for the same homeowners, so instant automated follow-up plus a quick personal call makes a difference.
Do cash-out refinances need different pages?
Yes. Cash-out has different goals and trade-offs (using equity for renovations or debt consolidation) and deserves its own page and FAQs.
Where can I see the latest PMMS data?
On Freddie Mac's PMMS page, which updates weekly on Thursdays.
Sources
- Freddie Mac Primary Mortgage Market Survey (2026-10-15)
- Freddie Mac PMMS historical weekly data (spreadsheet) (downloaded 2026-10-19)
- FFIEC / CFPB: 2023 HMDA data on mortgage lending (2024)
Statistics are quoted with source and date. Mortgage Website Shop is a website and marketing provider, not a lender; this article is general information, not legal or financial advice.