
Included in every plan
Mortgage website compliance, built into the design.
Every design has a compliance block your compliance team can approve once: NMLS IDs, licensing lines, Equal Housing Opportunity, privacy links and disclaimers in the right places. We explain what mortgage sites usually show. We do not give legal advice.
Definition
What is a mortgage advertising compliance?
Mortgage advertising compliance is the set of federal and state rules that govern what a lender or loan officer must and must not say in ads, including websites: identification such as NMLS IDs, fair-lending statements, and the disclosures required when specific terms like rates or payments are advertised.
NMLS IDs where expected
Your individual and company NMLS IDs, typically in the footer and on your profile.
Equal Housing Opportunity
The statement on every page; the official logo only when your company provides its approved asset.
State licence lines
Licensing language for each state you are licensed in, as your compliance team words it.
No trigger terms by default
We avoid advertising rates, payments or down payments that would require extra disclosures unless you approve them.
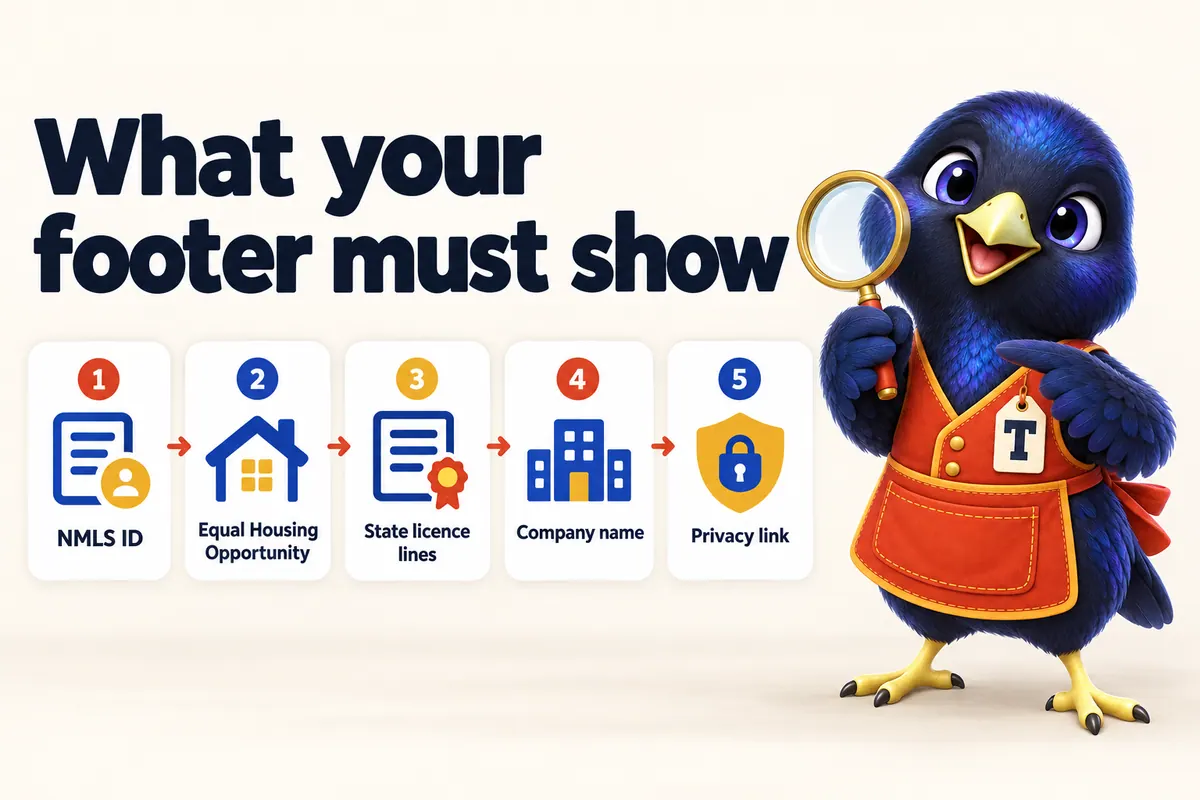
Anatomy of a compliant footer
- Identification. Individual and company NMLS IDs, as Regulation Z and the SAFE Act expect.
- Licensing. State licence language for each state you are licensed in.
- Fair lending. The Equal Housing Opportunity statement (official logo only from your company's approved asset).
- Policies. Privacy, terms, accessibility and NMLS Consumer Access links.
- Disclaimers. Wording your compliance team supplies.
Verify a licence on NMLS Consumer Access. Read the rule text in Regulation Z and HUD fair housing guidance.
Set-up
How compliance block get set up
-
01
Collect details
NMLS IDs, states, disclaimers.
-
02
Place them
Footer, profile, forms, calculators.
-
03
Compliance review
Your team approves the preview.
-
04
Keep current
Update when licences change.
What you get
- NMLS and licence placement
- Equal Housing statement
- Privacy, terms and accessibility pages
- Consent wording on forms
What it does not do
- Not legal advice: your compliance team approves
- Company-specific rules vary
- You must tell us when licences change
Which plans include compliance block?
MWS-SHELF
Shelf · $89/mo
Included
MWS-SHOWROOM
Showroom · $169/mo
Included
MWS-FLAGSHIP
Flagship · $289/mo
Included
Full details on the pricing page.
Works well with
Online application
A friendly 1003-style online mortgage application form for your website, or a button to your secure portal. Tr…
Loan program pages
Eight loan program pages written for your market: conventional, FHA, VA, USDA, jumbo, DSCR, HELOC and reverse.…
Blog & SEO content
Mortgage blog content written for you: researched, sourced posts with FAQs, schema and internal links. Include…
Help desk
Compliance block: questions and answers
01Does my website need my NMLS ID?
Generally yes. The SAFE Act and Regulation Z (12 CFR 1026.36(g)) require loan originator identification, including NMLS IDs, on certain materials, and most companies and states expect it on websites. Your compliance team confirms exactly where.
02Do I need the Equal Housing Opportunity logo?
Fair-lending advertising guidance expects an Equal Housing Opportunity statement or logo on mortgage advertising. We include the statement on every page and add the official logo if your company supplies the approved asset.
03What are trigger terms?
Under Regulation Z, advertising certain specific terms (such as a payment amount, number of payments, or down payment) triggers extra required disclosures. Our default copy avoids them; if you want to advertise terms, your compliance team writes the disclosures.
04Do you provide legal or compliance advice?
No. We explain what mortgage sites usually show and build it in. Your compliance officer or attorney approves the final wording.
05What about state licensing lines?
Many states expect licensing information. We add the lines your compliance team provides for each state you are licensed in.
06Is the site accessible?
We build to WCAG 2.2 AA: contrast, keyboard use, focus states, alt text and reduced-motion support, with an accessibility statement.
07Do co-marketing pages with realtors raise issues?
They can. RESPA Section 8 restricts referral fees and things of value. Co-marketing pages should be reviewed by your compliance team before launch.
08Where can borrowers verify my licence?
On NMLS Consumer Access. We can link your NMLS ID there.
Compliance block, done for you.
Pick a design and plan; compliance block comes set up and branded on launch day.